31 Jul 2026
教学人员

3917 1050
KK 1005
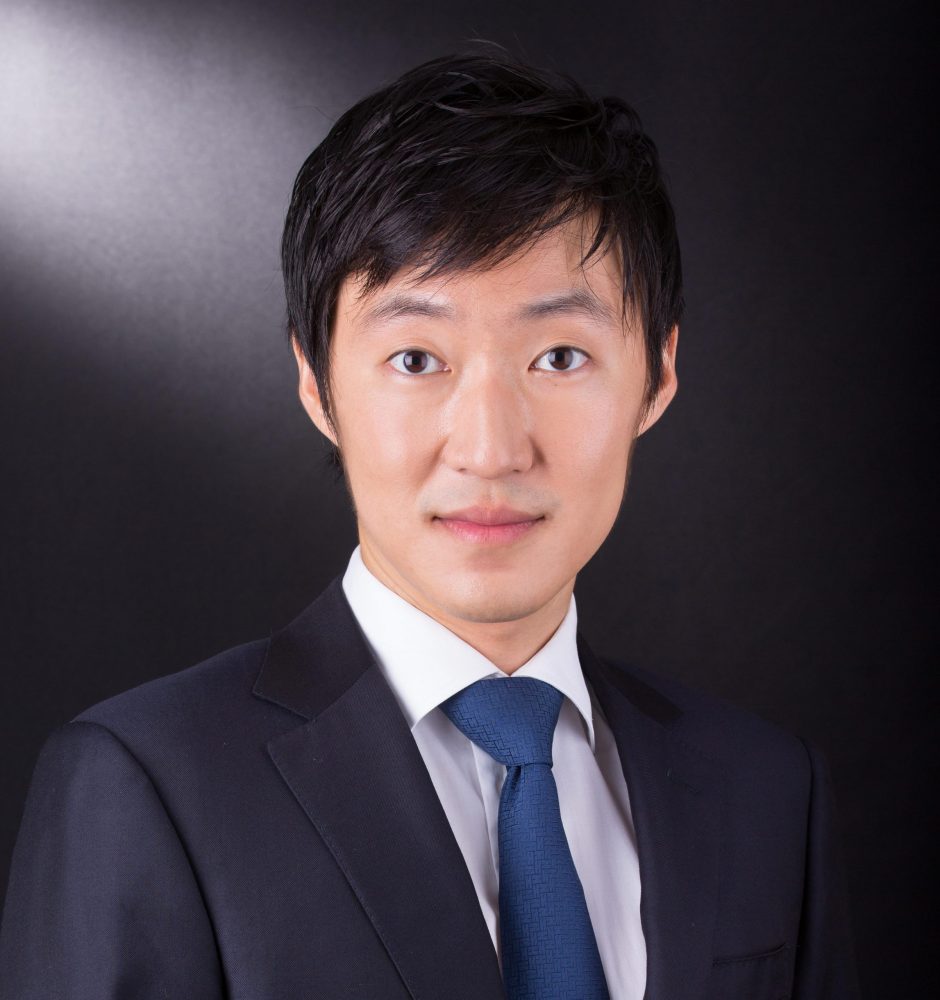
Dr. Yang Liu joined The University of Hong Kong in 2017. He is recognized as a National-level Young Talent. He is the founding co-director of the Wealth Management Academy and the founding director of the Master of Wealth Management Program. He serves as the associate editor of Management Science and Economic Letters.
His research interests span international finance and macroeconomics. He published in top academic journals such as Journal of Finance, Journal of Financial Economics, Review of Financial Studies, Journal of Monetary Economics, Journal of International Economics, Management Science, and won numerous research awards. He is the principal investigator or co-investigator of an NSFC Excellent Young Scientist Program, an NSFC Major Program, an NSSFC Major Program, an RGC Theme-Based Research Grant, an NSFC Emergency Program, an RGC Early Career Scheme, and multiple RGC General Research Funds. He was a visiting scholar at the International Monetary Fund and a research associate at the Federal Reserve Bank of Philadelphia. He received his Ph.D. in Economics from the University of Pennsylvania and Bachelor of Economics from Fudan University. His research and policy analysis have been widely featured in media such as the Xinhua, Financial Times, Associated Press, AFP, VOA, China Daily, SCMP, HKEJ, Ming Pao, Wen Wei Po, Ta Kung Pao, HK01, Hong Kong TVB, Master Insight, RTHK, Tencent, Sina, NetEase, Sohu, Toutiao, Yahoo, Phoenix News, Economy Chosun, among others.
For details, please visit www.yangliuresearch.com.
香港金融管理局以本地银行体系为锚,本年4月发出首批稳定币发行人牌照后,外界对银行业参与稳定币发行寄予厚望。合规银行既可借此提升支付与结算效率,也有望拓展跨境金融服务,并推动数字资产生态与实体经济进一步连接。
随着全球货币数字化发展日趋成熟,稳定币市场正酝酿一项意义重大的新动向。据报道,Visa、Stripe等逾百家金融与科技机构联手组成 Open Standard 联盟,预计于年内推出美元稳定币 Open USD。
香港大学经管学院金融学副教授刘洋表示,全球地缘政治环境变迁强化了香港的相对优势,高净值人士越来越倾向将资产分散至多个司法辖区,近年来许多亚洲客户将财富重新转回香港。
Lack of comovement between consumption differentials and real exchange rates is a traditional indicator of a disconnect of foreign exchange markets from economic fundamentals. We present novel empirical evidence for the disconnect between the volatilities, as opposed to the levels, of these variables. The volatility correlations are below one, but they are larger than the level correlations. We discuss the economics of volatility disconnect anomaly in settings with complete and incomplete markets and provide an explanation of our empirical findings based on international risk sharing of expected growth and volatility news shocks.
2026年4月,香港金融管理局向香港上海汇丰银行有限公司和碇点金融科技有限公司发出首批稳定币发行人牌照。汇丰是香港最大的银行之一,兼有发钞行的特殊地位。
2026年4月,香港金管局向汇丰银行和碇点金融发出稳定币牌照,港元稳定币发行破冰在即。这是稳定币作为链上金融基础设施在香港正式启航的重要标志。“十五五”规划纲要明确提出巩固提升香港国际金融、贸易中心地位,强化国际资产与财富管理中心功能。
Do real assets protect against inflation? Stocks’ core inflation betas are negative, while their energy betas are positive. Currencies, commodities, and real estate mostly hedge against energy inflation, but not core inflation. These hedging properties are reflected in the prices of inflation risks: only core inflation carries a negative risk premium, and its magnitude is consistent within and across asset classes, uniquely among macroeconomic risk factors. Energy inflation has become more procyclical and volatile since the 1990s, which helps explain the time-varying correlation between stock and bond returns. A two-sector New Keynesian asset pricing model accounts for these facts quantitatively.
2025年8月1日,香港《稳定币条例》生效,标志著中国将逐步参与稳定币市场,并探索如何通过香港这一离岸金融中心,利用稳定币推动人民币国际化。 要回答这一问题,我们需要在当前市场情绪高涨的背景中,理性、客观地理解离岸人民币稳定币的发展逻辑。
This paper proposes a conditional asset pricing model that integrates environmental, social, and governance (ESG) demand and supply dynamics. Shocks in the demand for sustainable investing represent a novel risk source, characterized by diminishing marginal utility and positive premium. Green assets exhibit positive exposure to ESG demand shocks, hence commanding higher premia. Conversely, time-varying convenience yield leads to lower expected returns for green assets. Moreover, ESG demand shocks have positive contemporaneous effects on unexpected returns, contributing to large positive payoffs in the green-minus-brown portfolio over extended horizons. The model predictions align closely with evidence on return spreads between green and brown assets, further reinforcing the apparent gap between realized and expected spreads.